• Добро пожаловать на инвестиционный форум!

    Во всем многообразии инвестиций трудно разобраться. MMGP станет вашим надежным помощником и путеводителем в мире инвестиций. Только самые последние тренды, передовые технологии и новые возможности. 400 тысяч пользователей уже выбрали нас. Самые актуальные новости, проверенные стратегии и способы заработка. Сюда люди приходят поделиться своим опытом, найти и обсудить новые перспективы. 16 миллионов сообщений, оставленных нашими пользователями, содержат их бесценный опыт и знания. Присоединяйтесь и вы!

    Впрочем, для начала надо зарегистрироваться!
  • 📝 Знаешь буквы и умеешь их компоновать? Платим. Дорого. Бессрочная акция от MMGP: "ОПЛАТА ЗА СООБЩЕНИЯ"

HFMarkets (hfm.com): Market analysis services. - Страница 49

Магазин готовых аккаунтов, сообществ и профилей

HFblogNews

Профессионал
Регистрация
13.01.2021
Сообщения
1,128
Реакции
1
Поинты
11.170
Date: 21st October 2026.

Tech Earnings Ease AI Fears, Asian Stocks Rally.

Tech Earnings Ease AI Fears, Asian Stocks Rally


Strong tech earnings are giving the AI trade a much-needed lift. Asian stocks climbed on Wednesday after better-than-expected results from SpaceX and Super Micro Computer, with Korean shares rallying as much as 4%, Japan’s Nikkei up 1.3% and Taiwan’s Taiex gaining 1.2%. Nasdaq 100 futures rose 0.8%, and European shares were set to open higher.

The bigger test comes later today, when Meta and Tesla report. Meanwhile, Brent is holding above $110, Australia’s central bank has turned more hawkish, and a cluster of central bank decisions next week will keep rate expectations in focus. Here is what traders need to know.

AI trade: earnings beats bring relief​

Results are helping to calm the AI anxiety that drove last week’s sell-off. SpaceX rose 8.1% in extended trading after its numbers, while Super Micro Computer jumped 16%. The MSCI Asia Pacific Index gained 1%, ending a two-day losing streak.

Wall Street also ended Tuesday on a positive note, with the S&P 500 up 0.3% as oil prices and Treasury yields eased. Early results this season have helped steady sentiment, though investors remain selective after last week’s sell-off.

AI infrastructure stocks remain volatile. Elice surged 30% in Seoul, recovering part of its record-breaking IPO slump, but Australian data-centre developer NEXTDC plunged 40% after cutting its outlook.

Not everyone is convinced. Billionaires Ken Griffin and Ray Dalio have both recently warned that AI has the hallmarks of a bubble. Edward Jones’ Angelo Kourkafas takes a more balanced view, arguing that demand isn’t slowing. In his view, investors are simply becoming more selective, favouring companies with the strongest finances.
Corporate highlights​

  • SpaceX and Tesla: Elon Musk said both companies have formed special committees to explore a potential merger, which would be the largest corporate tie-up ever.
  • Netflix: The company posted its slowest revenue growth in three years and guided for a fourth straight quarter of slowing growth.
  • CATL: Shares fell after third-quarter profit growth missed estimates.
  • Nvidia: The chipmaker is reportedly in talks to invest hundreds of millions of dollars in Australian AI cloud firm Firmus Grid.
  • DayOne Data Centers: The company is weighing a delay or a smaller size for its US IPO.

Oil: Brent holds above $110​

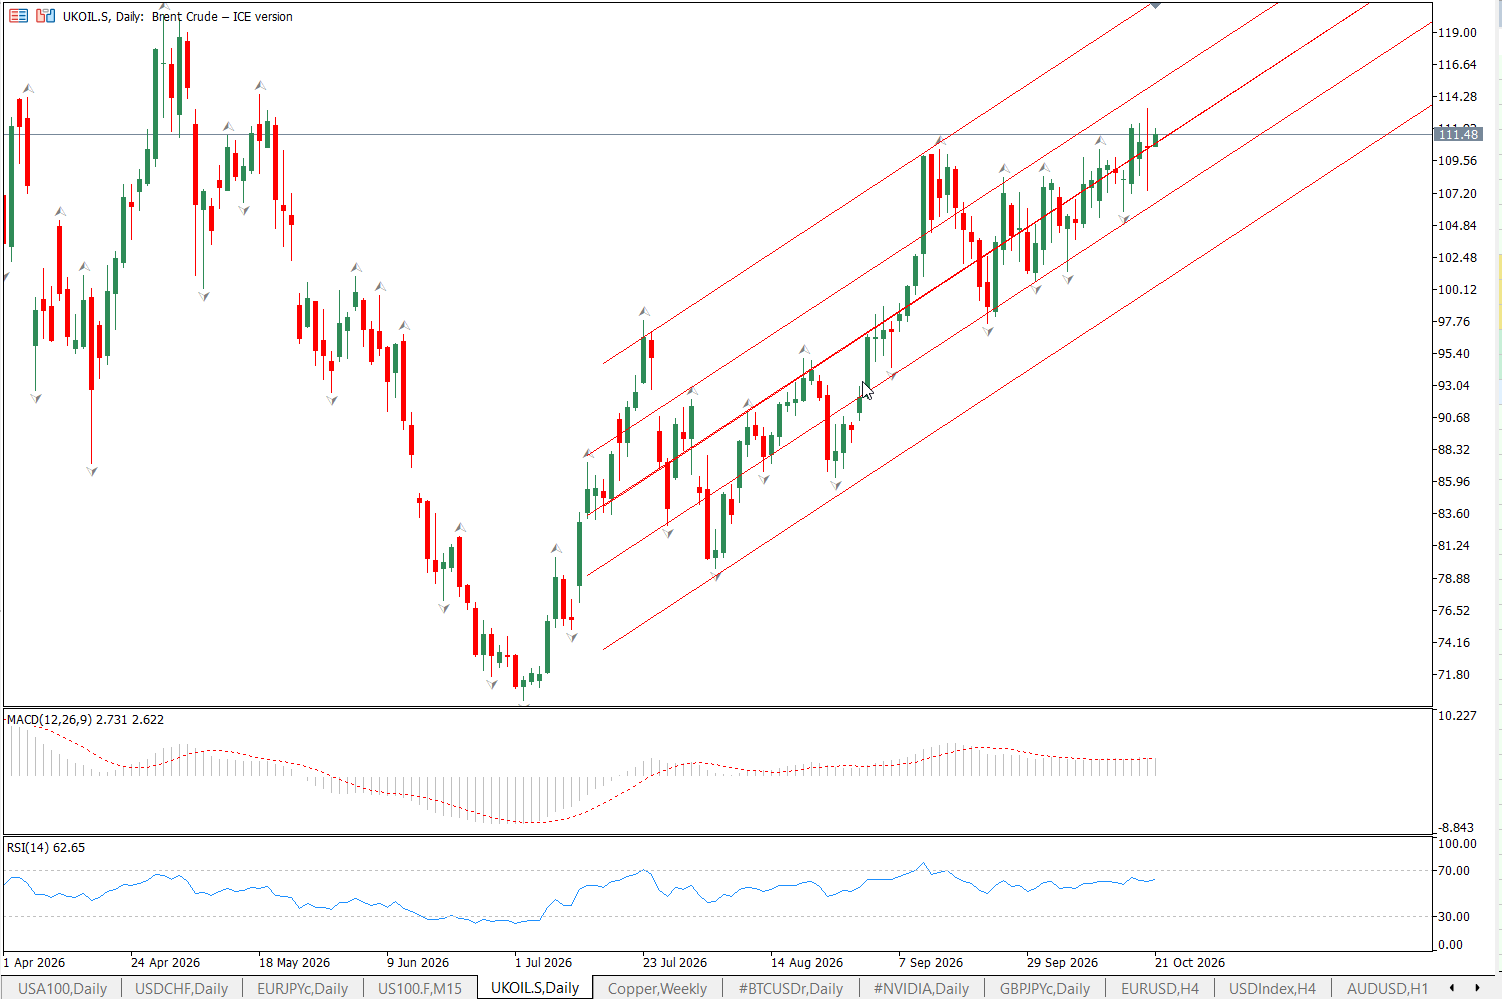
Brent rose 1.1% to around $110.03 a barrel after touching a five-month high in a volatile session on Tuesday. Prices briefly dipped on unconfirmed reports of renewed peace talks, then recovered after the reports were denied.

2026-10-21 07_42_30-48132278 - HFMarketsGlobal-Demo - Netting - HF Markets (SV) Ltd. - [UKOIL.S,Dail


Traders are balancing diplomacy against supply risks. On the diplomacy side, the Iranian president met Pakistan’s army chief, a key mediator between the US and Iran. On the risk side, Houthi attacks on Saudi infrastructure and reported vessel attacks in the Gulf continue, and US industry data showed another drop in crude stockpiles.

On Ukraine, US envoy Steve Witkoff is due to meet Russian President Vladimir Putin today, following talks with Ukrainian President Volodymyr Zelenskiy in Norway that a US official described as constructive.
Central banks: RBA turns hawkish, Fed hold expected​

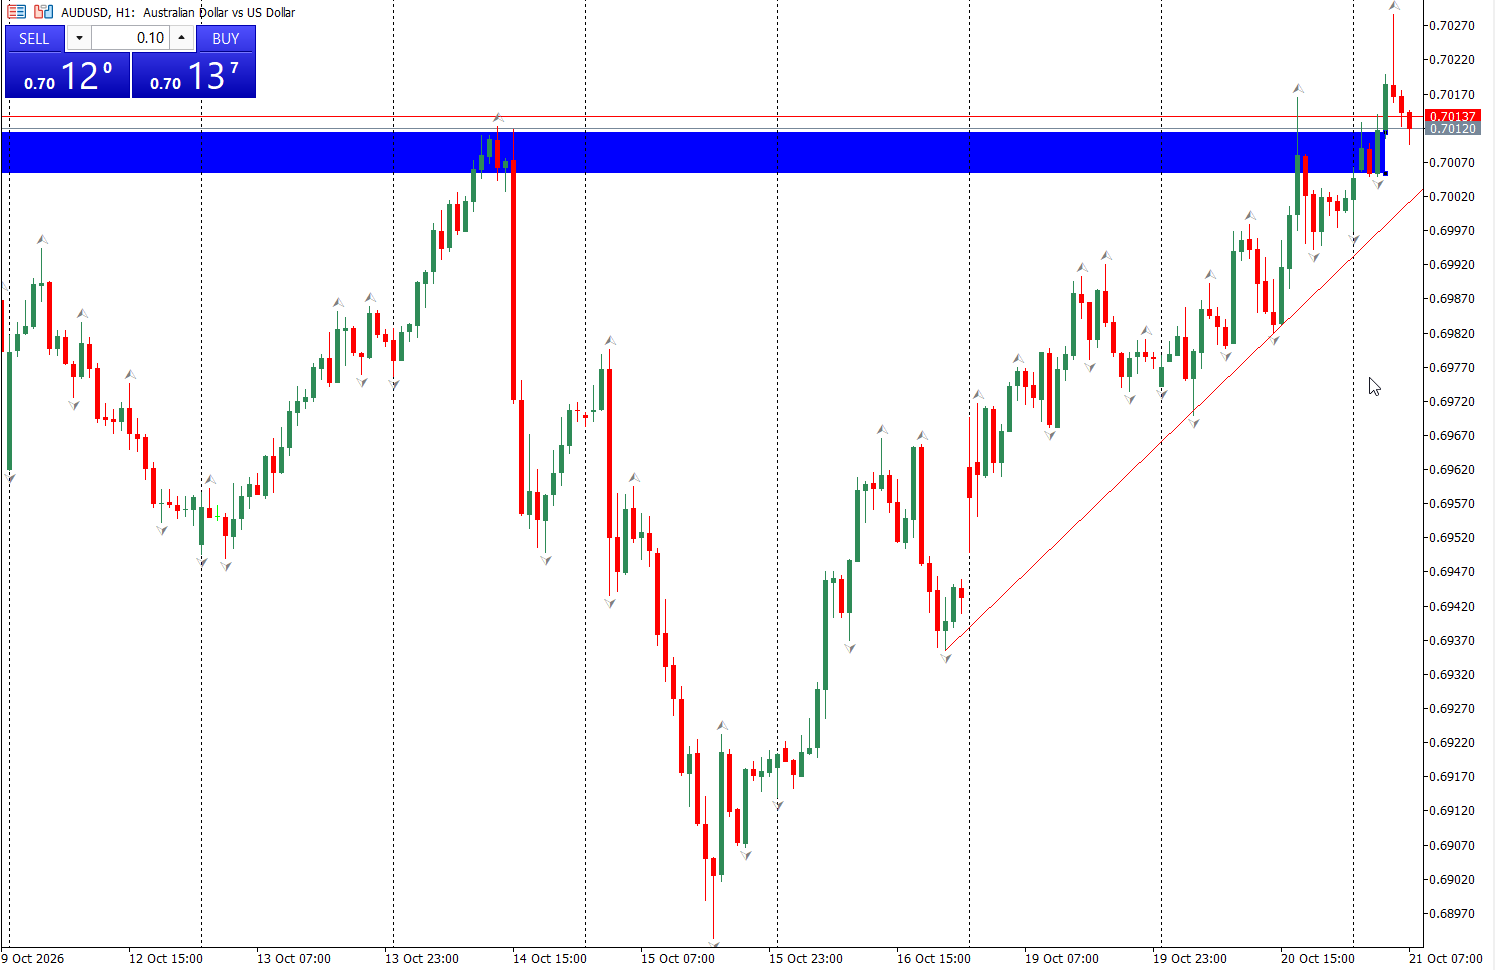
RBA. RBA Deputy Governor Andrew Hauser said the inflation outlook looks materially worse, partly due to high oil prices, and that he is unsure whether rates will need to rise again in November. Markets now see roughly a 50% chance of a hike to 4.85% at the 2–3 November meeting, up from 30% at the start of the week. Goldman Sachs now expects a hike. AUD/USD hovered near a three-week high at 0.7013. Australia’s Q3 CPI, due next week, is forecast to show headline inflation at 4.0%.

2026-10-21 07_38_40-48132278 - HFMarketsGlobal_[AUDUSD,H1]


Fed. A Reuters poll shows most economists expect the Fed to hold on 28 October before hiking in December. CME FedWatch prices an 83% chance of a hold. The US 10-year yield edged up 1 basis point to 5.12%.

BoJ. Economists also expect the Bank of Japan to hold on 30 October, with a 25bp hike in December followed by quarterly increases. USD/JPY rose 0.1% to 158.33 after Japan’s September exports grew 16.7% year on year, below estimates but supported by strong chip and AI-related demand.

Next week’s lineup. The Fed, ECB and BoJ announce decisions on consecutive days from Wednesday 28 October. The Reserve Bank of New Zealand and the Bank of Canada also decide on 28 October, with markets betting on 25bp hikes from both.

FX and bonds: dollar near three-week low, French risk persists​

The dollar index held at 101.78 after hitting a three-week low on Tuesday, as lower yields and oil prices reduced its appeal. CBA’s Carol Kong noted that tech earnings could have a big impact on the dollar, given how closely global sentiment is tied to the sector.

  • EUR/USD: steady at 1.1229
  • GBP/USD: 1.33735
  • NZD/USD: −0.1% to 0.5677
  • USD/CAD: steady at 1.4064
France remains the euro’s main risk. Prime Minister Sébastien Lecornu said troops will reinforce police ahead of protests planned for Saturday. French stocks fell, and the 10-year OAT yield rose 2.7 basis points to 4.94%. That widened its spread over German Bunds to 153.1 basis points.

Emerging markets. Traders are awaiting Bank Indonesia’s decision today, as the central bank tries to halt the rupiah’s slide following the MSCI-triggered market rout.

Gold and crypto​

Gold traded near $4,120 an ounce, holding onto losses of more than 1% since the start of the week. Bitcoin rose 0.3% to about $82,989, and Ether gained 0.2% to roughly $2,453.

Three things to keep in mind:​

  • Meta is today's market mover. Its AI spending guidance could swing the Nasdaq 100 and Asian chip stocks, so expect volatility after the US close.
  • AUD is in play. A hawkish RBA and next week's CPI make AUD/USD sensitive to any inflation surprise.
  • Central bank week is approaching. Five major decisions in three days mean positioning could shift quickly. Review position sizes and stop-loss levels.
Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

Please note that times displayed based on local time zone and are from time of writing this report.


Click HERE to access the full HFM Economic calendar.

Want to learn to trade and analyze the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

Click HERE to READ more Market news.

Andria Pichidi
HFMarkets

Disclaimer:
This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.
 
Реклама: 🔥 Хочешь получить Telegram Premium и стать гуру Polymarket? Кликай сюда!
HFblogNews

Профессионал
Регистрация
13.01.2021
Сообщения
1,128
Реакции
1
Поинты
11.170
Date: 23rd October 2026.

AI Sell-Off Sparks Flight to Safety as Oil Tops $114: What Traders Need to Know.


AI Sell-Off Sparks Flight to Safety as Oil Tops $114: What Traders Need to Know


A sharp tech sell-off on Wall Street has triggered a global flight to safety. On Thursday the Nasdaq 100 fell 2.9%, its worst day since June, and the S&P 500 dropped 1.2%. Investors poured into US Treasuries, Japanese government bonds and the Yen. Asian markets opened sharply lower on Friday but recovered much of the damage by midday, and Nasdaq 100 futures edged up 0.1%.

The risk backdrop remains tense. Brent crude climbed above $114 a barrel, and next week brings results from Microsoft, Amazon and Alphabet alongside decisions from the Fed, ECB and BoJ. Here is what traders need to know.

Tech stocks: Asia claws back early losses​

Asian tech stocks staged a notable intraday recovery. South Korea's Kospi fell as much as 4.1% before paring losses to trade roughly flat, as SK Hynix reversed early weakness to rise 4%. The MSCI Asia Pacific Index trimmed a 1.1% drop to just 0.2%.

The bigger picture remains weak, however:
  • Nikkei 225: Fell as much as 2%, taking its weekly drop to almost 4%. SoftBank fell 6% and is down nearly 15% this week, while wafer maker Sumco dropped 7.8%.
  • CSI 300: Fell about 1% and remains in a bear market, more than 20% below its late-June peak.
  • Taiwan: Markets were closed due to a typhoon warning.
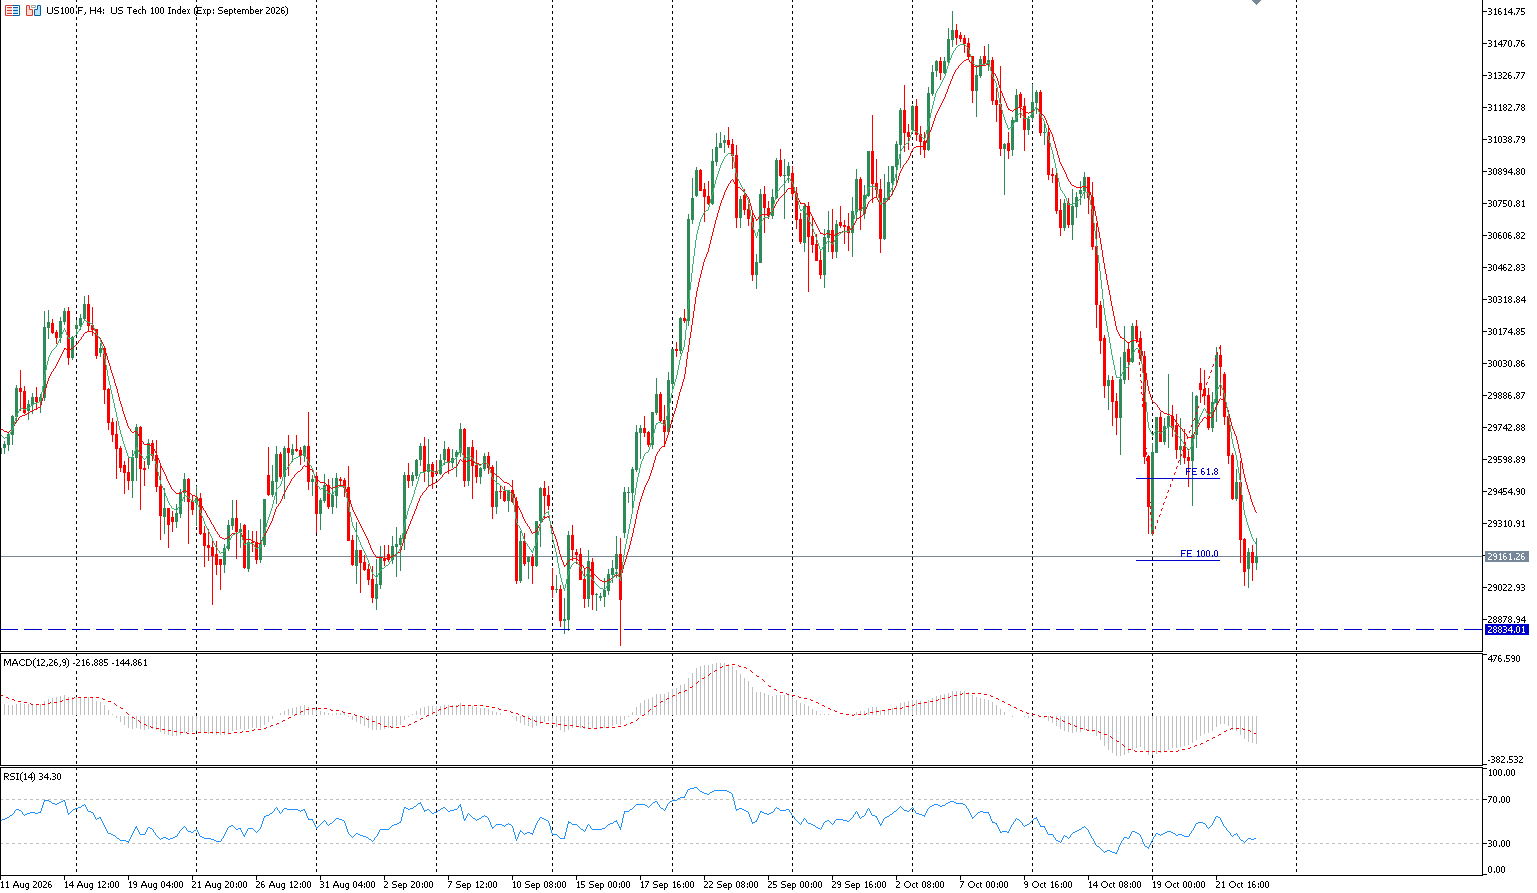
In the US, the Nasdaq 100 is heading for back-to-back weekly losses for the first time since July. The Philadelphia Semiconductor Index is on track for a third straight weekly decline, its longest losing run since November 2025. Meta's spending plans revived doubts about debt-funded AI infrastructure.

2026-10-23-10-51-50-48132278-hfmarketsglobal


Is it a bubble? Opinions are split. Matsui Securities' Tomoichiro Kubota warned that the AI bubble may have started to burst, as falling share prices make it harder for AI firms to raise capital. Julius Baer's Mark Matthews disagrees, arguing that demand still far exceeds supply and that big chip corrections are buying opportunities. Blackstone President Jon Gray also rejected the bubble view, describing demand for AI as almost parabolic.

Rotation into defensives
Money leaving tech is flowing into defensive sectors. The S&P 500 Consumer Staples Index jumped 3.1% on Thursday to a record high and is on course for its best month since 1998. Utilities and healthcare also gained.

Credit markets are showing strain too. Spreads on dollar bonds from higher-rated Asian companies widened to their highest since last July.

Bonds: Biggest Treasury rally in over two years​

Treasuries staged their biggest rally in more than two years on Thursday. The 10-year yield fell 17 basis points and dropped below 5% for the first time in a month, as traders unwound bearish positions. The yield edged back up to around 4.97% on Friday.

Three forces drove the buying: the AI sell-off, turmoil in French markets and renewed Middle East tensions. The rally has also led traders to scale back expectations of further Fed rate hikes.

Not everyone expects it to last. ING analysts still see the 10-year yield returning above 5% eventually, given inflation, fiscal deficits and AI-related trends. They said the risk-off mood eases pressure on the Fed to hike next week.

In Japan, the 10-year JGB yield fell 9 basis points to 2.77%, extending its rally to a fifth day on what Tokyo traders described as unusually heavy buying.

FX: Different safe havens for different risks​

Safe-haven demand is spreading across currencies, but OCBC analysts note that each risk favours a different currency:

  • AI jitters favour the yen. USDJPY dropped to 156.08 on Friday, the Yen's strongest level in over a month, before recovering to about 156.89. The Yen is set for a 0.7% weekly gain, its biggest since early September.
  • Middle East tensions support oil-linked currencies. The Canadian dollar strengthened past 1.40 per US dollar, its firmest in a month.
  • French fiscal stress supports the Swiss franc. USDCHF held near 0.8211, close to a one-month low.
Elsewhere, the dollar index edged up to 101.64 after touching 101.44 on Thursday, its lowest since the start of the month. EURUSD was flat at 1.121, weighed by concerns over France's debt. AUDUSD held at 0.7015, NZDUSD rose 0.2% to 0.5695, and the offshore Yuan traded near a four-year high at 6.6729.

Oil: Brent heads for third weekly gain

Brent rose 1% to around $114.35 a barrel, building on Thursday's 4% surge. Intensifying Houthi attacks on Saudi Arabia have raised fears of wider supply disruption, and Oil is set for its third consecutive weekly gain.

Notably, falling yields and a firmer Yen suggest markets are currently more worried about economic growth than inflation, even with Oil above $110.

UK: Retail sales disappoint​

British retail sales fell 0.4% in September, worse than the 0.1% drop expected. Warm weather hurt clothing sales, and supermarket volumes fell. Over the three months to September, sales volumes still rose 0.7%.

Consumer confidence in October posted its sharpest monthly fall since early in the COVID-19 pandemic. That comes ahead of next week's budget from finance minister John Healey and as markets weigh the Bank of England's next move.

What Could Move Markets Next Week?​

The key question is whether this week's flight to safety holds. Next week's results from Microsoft, Amazon and Alphabet will be the first real test. Strong numbers backed by clear returns on AI spending could pull money back into tech and push Treasury yields above 5% again. Another round of disappointment would likely extend the rally in bonds, the Yen and defensive stocks.

Central banks add a second layer of risk. The Fed decides on Wednesday 28 October, and markets expect a hold. This week's risk-off move has eased the pressure to hike. The BoJ follows on Friday, with Japan's inflation now above target, so any hint of a December hike could strengthen the Yen further.

Investors also face the UK budget and French protests this weekend, with the US midterms close behind. Hitoshi Asaoka of Asset Management One warned that this run of events could keep markets unsettled for longer than usual.

Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

Please note that times displayed based on local time zone and are from time of writing this report.


Click HERE to access the full HFM Economic calendar.

Want to learn to trade and analyse the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

Click HERE to READ more Market news.

Andria Pichidi
HFMarkets

Disclaimer:
This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.
 
Реклама: 🔥 Хочешь получить Telegram Premium и стать гуру Polymarket? Кликай сюда!
HFblogNews

Профессионал
Регистрация
13.01.2021
Сообщения
1,128
Реакции
1
Поинты
11.170
Date: 26th October 2026.

Markets Brace for Five Central Bank Decisions & UK Budget.


Markets Brace for Five Central Bank Decisions & UK Budget

Financial markets are preparing for a pivotal week, with key developments expected to influence investors and multiple asset classes. The currency market and Gold will particularly likely to see strong volatility as five central banks confirm their rate decisions.

These central banks include the Reserve Bank of New Zealand, the Bank of Canada, Federal Reserve, the European Central Bank, and the Bank of Japan. In addition to central bank decisions, the UK will also release its Autumn Budget. This is a key event for the FTSE 100, Euro and the Pound. However, the most influential event is likely to be the Federal Reserve’s rate decision and press conference on Wednesday evening.

During Monday’s open, the best-performing currencies are the Euro, Swiss Franc and British Pound. The worst-performing are the US Dollar, Australian Dollar, and Japanese Yen.

Euro - Moody Ratings Provides Limited Relief For European Investors​

The Euro is one of the best-performing currencies of the day due to opening with a bullish price gap. The price gap measures 0.15% and, so far, is holding onto its gains. The bullish price movement is due to the high bond yields, de-escalation in France, and the upcoming European Central Bank decision.

France’s de-escalation, particularly the fact that the country has avoided any riots and further strikes over the weekend, has been key. In addition, Moody’s has confirmed it will not downgrade France’s credit rating. These developments are supporting investor sentiment, but long-term pressures remain.

Moody’s said slower growth and a higher deficit have pushed France’s debt burden higher than previously expected, with bond yields rising more rapidly than expected. For this reason, the price of the Euro remains at risk in the long term. Investors will be paying close attention to the ECB’s press conference for comments on these developments.

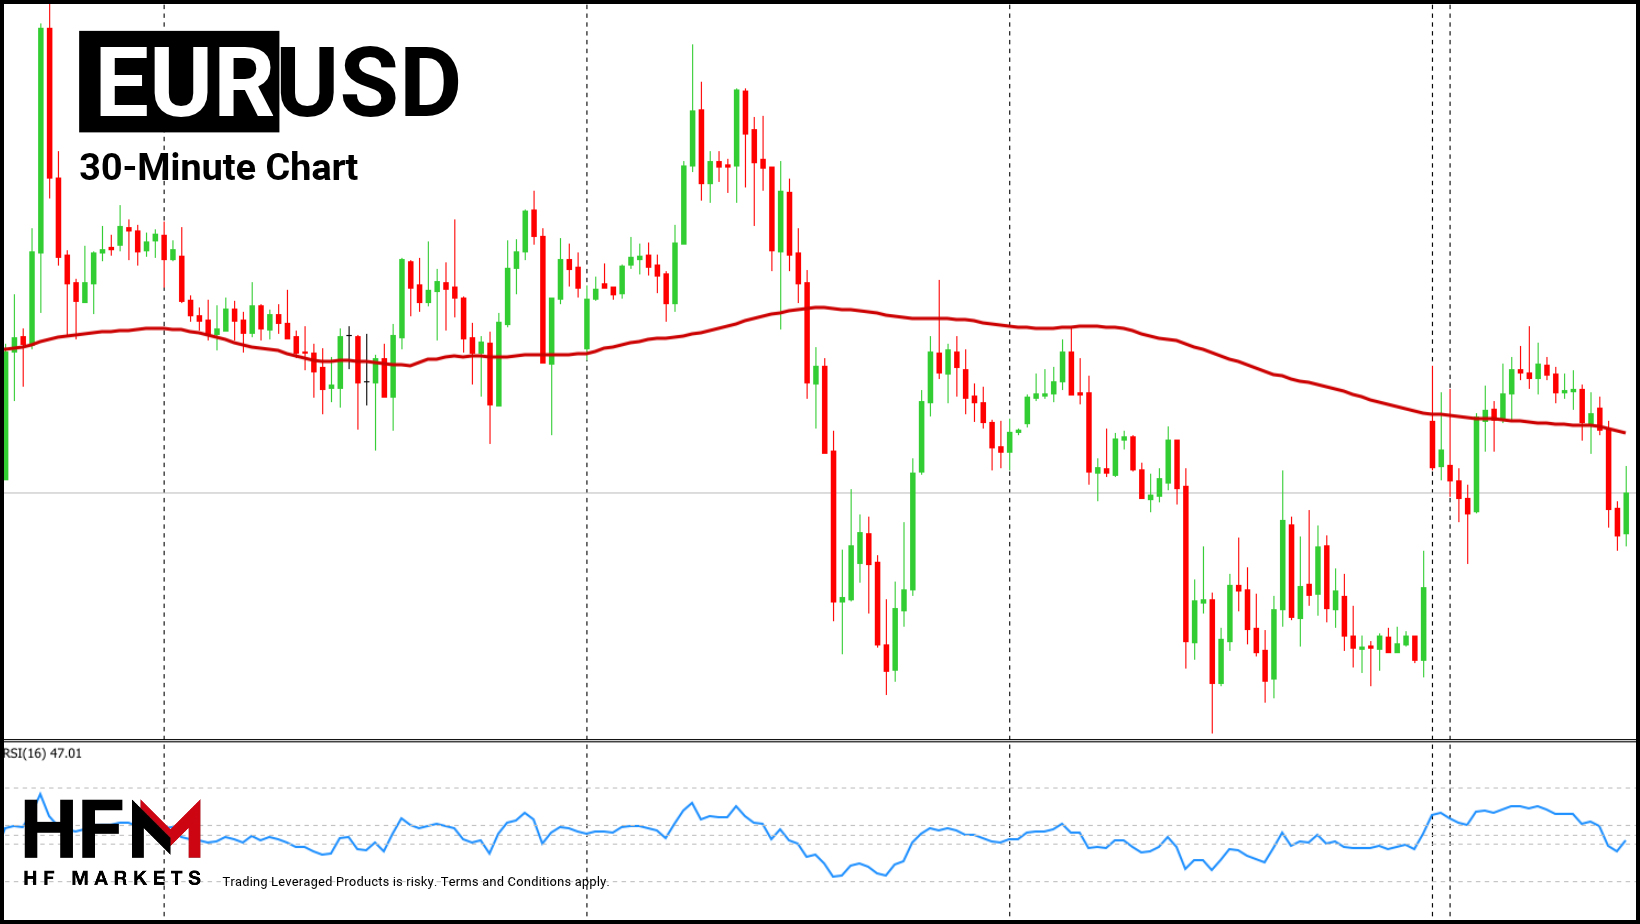
Technical indicators across most timeframes continue to suggest a bearish outlook, despite the day’s bullish price movement. While shorter timeframes show signs of modest bullish momentum, a decline of just 0.08% could be enough to reverse these signals. Therefore, monitoring price action remains essential in determining the market’s next direction.

HFM - EURUSD 30-Minutes

HFM - EURUSD 30-Minutes

The US Dollar Falls But Aims to Rebound - Traders Eye Elections & Fed Guidance​

The US midterms are only a week away, and investors have one eye on the Federal Reserve and the other on the elections. The market expects the Federal Reserve to keep interest rates at 4.00% but comments on a December hike will impact demand. If the Fed seems particularly hawkish, the US Dollar could rise further.

Oil prices are declining again on Monday, as are bond yields. The 10-year bond yield is currently trading at 4.974%, only the second time in October that the yield has fallen below 5.00%. The lower bond yields and oil prices are pressuring the US Dollar. However, both oil prices and bond yields remain high, and the price movement will depend largely on the Federal Reserve and the midterms.

This afternoon’s CB Consumer Confidence Index could provide some volatility for the US Dollar. A higher-than-expected figure could support the currency. If the US Dollar Index rises to 101.66, traders will start contemplating the breakout level and resistance level. This is a key price for the US Dollar Index. So far, bullish momentum is again gaining pace for the Dollar as the European open edges closer.

Great British Pound - Autumn Budget To Signal GBP Outlook​

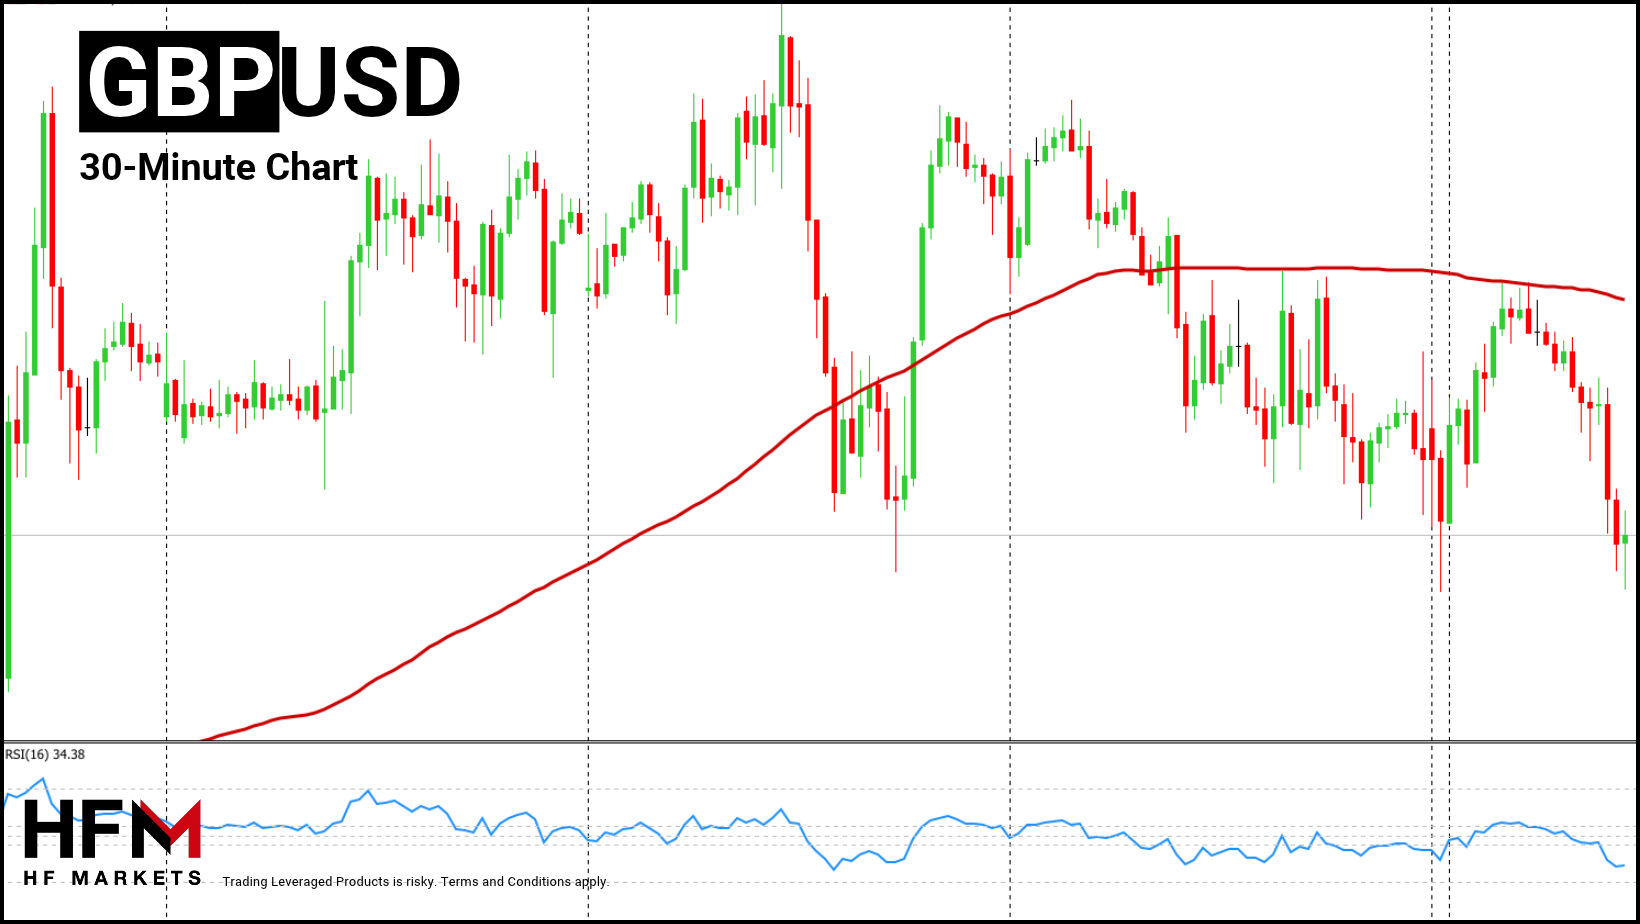
The British Pound has been the best-performing currency of the past month as the UK’s economic data has outperformed previous market expectations. However, its outlook will massively depend heavily on the autumn budget.

Markets will closely monitor government spending, taxation, and borrowing plans, particularly as elevated inflation and rising debt-servicing costs continue to challenge the UK economy. A fiscally disciplined budget could support sterling, while concerns over government borrowing may weigh on the currency.

Investors need to feel that the UK’s economy can continue performing without prompting borrowing concerns. This is particularly vital as the Bank of England has been one of the central banks yet to increase rates.

HFM - GBP/USD 30-Minute Chart

HFM - GBP/USD 30-Minute Chart

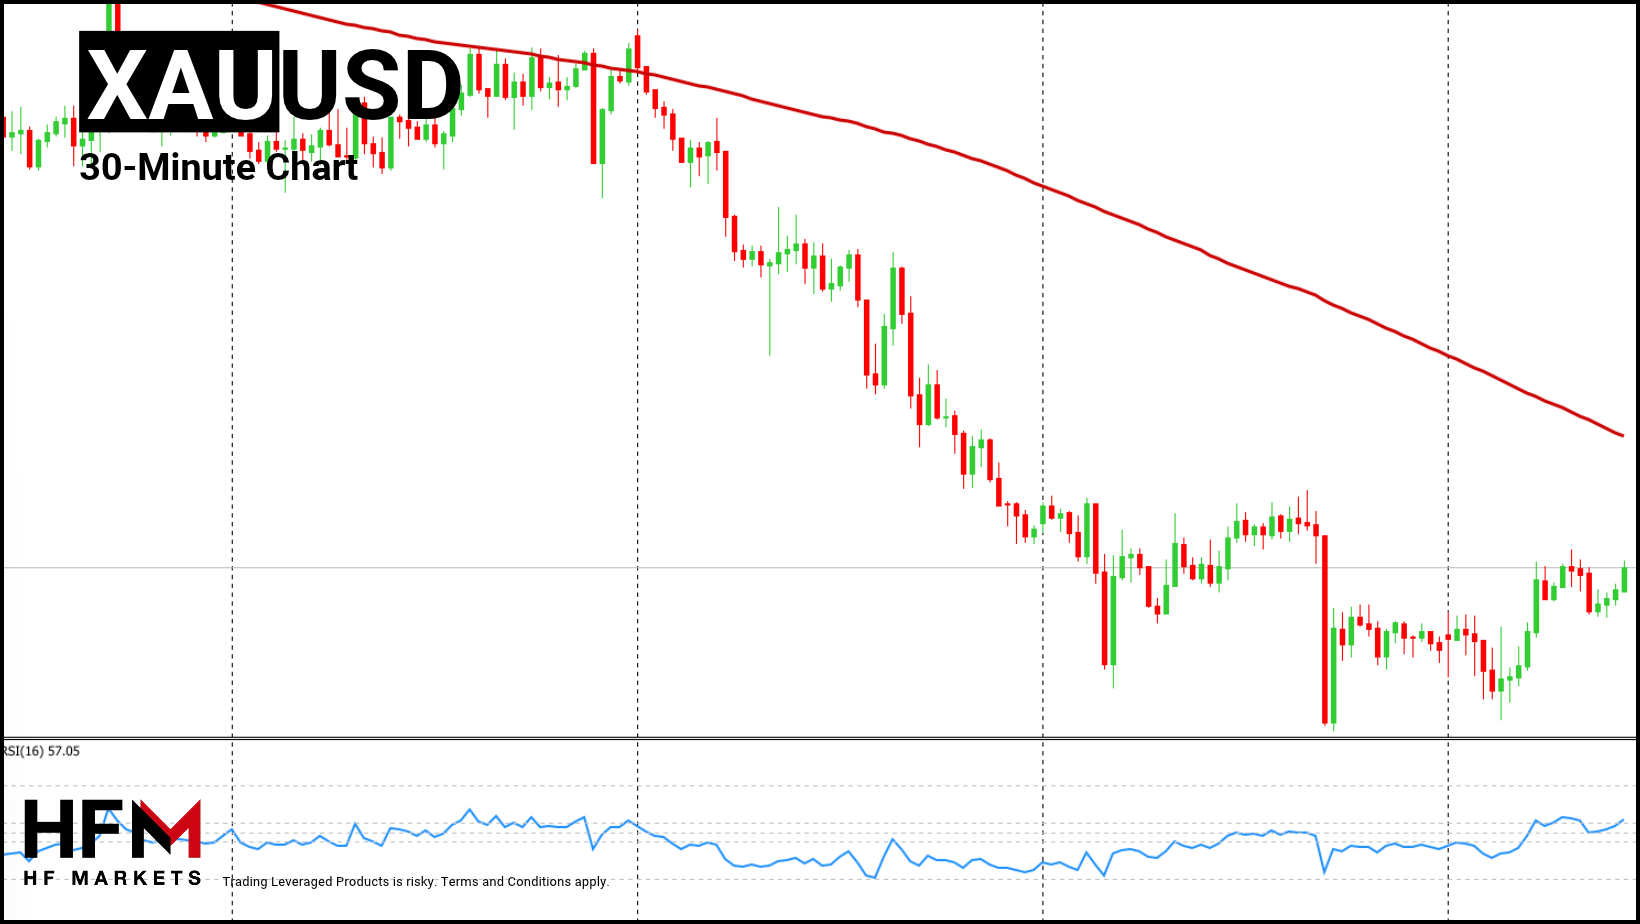
Gold - More Bad News Mounts on XAU/USD​

Gold has fallen to its lowest level since July 2026. Gold is also now trading close to the $4,000 psychological price, which many economists have previously advised said they see as its intrinsic value. Under the current market conditions, the decline in Gold prices may seem strange.

The decline is being driven by three main developments. Markets expect the Fed and most central banks to continue hiking into 2027 and struggle to bring rates down in the long term. Investors are also raising funds by selling Gold in order to cover stock market losses.

Lastly, investors are turning to the bond market, which is paying high yields. In other words, investors are switching from Gold to Bonds as their preferred safe haven. In addition, high long-term oil prices are also pressuring Gold while supporting the Dollar.

HFM - Gold 30-Minute Chart

HFM - Gold 30-Minute Chart

The key support levels can be seen between $3,943 and $4,000. For the price to maintain momentum below this level, investors would need to see a strong price driver.

Key Takeaways:​

  • Five major central banks prepare to announce interest rate decisions, potentially triggering market volatility.
  • The Euro strengthens as political tensions in France ease and Moody’s maintains its credit rating.
  • The US Dollar weakens amid falling bond yields, while the Pound awaits the UK Autumn Budget.
  • Gold remains under pressure near $4,000 as high bond yields and rate hike expectations weigh on demand.

Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

Please note that times displayed based on local time zone and are from time of writing this report.


Click HERE to access the full HFM Economic calendar.

Want to learn to trade and analyze the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

Click HERE to READ more Market news.

Michalis Efthymiou
HFMarkets

Disclaimer:
This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.
 
Реклама: 🔥 Хочешь получить Telegram Premium и стать гуру Polymarket? Кликай сюда!
Сверху Снизу